Keep the two vehicles and prices distinct
Record the proposed vehicle’s agreed cash price separately from the allowance offered for the existing vehicle. Note the date, conditions and validity of each quote. A part-exchange discussion concerns a vehicle transaction, not selling selected physical parts while keeping the rest of a car. Ask what happens if the vehicle’s recorded condition or the agreed handover date changes.
Confirm any finance position independently
If an existing agreement is involved, obtain the actual position and settlement information from the finance provider through its proper route. MoneyHelper’s UK guidance explains that exiting an agreement can involve conditions and costs and discusses requesting a settlement figure. Do not guess ownership, permission to sell or an early-termination route from this worksheet. Get appropriate advice for the actual agreement and jurisdiction.
Show the arithmetic and its boundary
For a clearly defined illustrative case, start with purchase price, subtract the agreed allowance, then add a separately confirmed settlement amount and itemised additional charges where they apply. State whether the quoted figures already include any of those elements to avoid double counting. This is a way to reconcile a quote, not an assertion that every transaction uses the same payment structure or that a lender has approved it.
Compare the complete commitment
Ask the seller and finance provider to explain who receives which amount and which obligations remain. Keep any new finance terms separate from the simple changeover arithmetic: a monthly payment alone does not reveal the total commitment. Retain dated written quotes and unresolved questions. An advertised estimate is not a completed valuation, actual sale or proof that a car is affordable for the buyer.
Read the drawing as text
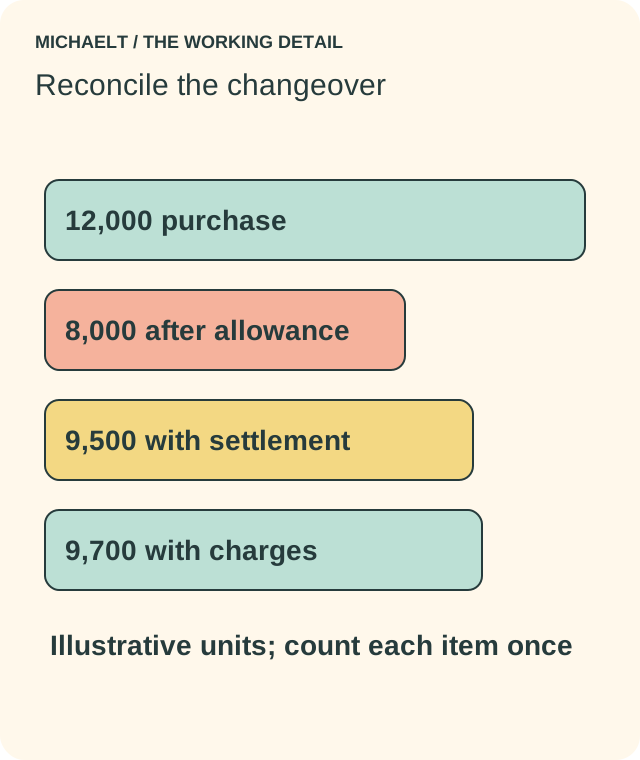
Illustrative 12,000 purchase minus 4,000 allowance gives 8,000. Add separately applicable settlement 1,500 and charges 200: 9,700. Avoid counting any item twice.
Work through an example
In a fictional same-currency example, purchase price is 12,000 units, allowance is 4,000, separately confirmed existing settlement is 1,500 and itemised additional charges are 200. Where none is already included elsewhere, the illustrated amount to reconcile is 12,000 − 4,000 + 1,500 + 200 = 9,700 units. Financing interest and future running costs are outside that arithmetic.
Illustrative example; figures, people and organisations in the worked record are fictional.
The example record
Purchase price
- Illustrative units
- 12,000
- Role
- Start
Allowance
- Illustrative units
- 4,000
- Role
- Subtract once
Confirmed settlement
- Illustrative units
- 1,500
- Role
- Add only if applicable and separate
Additional charges
- Illustrative units
- 200
- Role
- Itemise, avoid double counting
Illustrated changeover
- Illustrative units
- 9,700
- Role
- Not a finance approval
Download blank worksheet (.csv) ↗Download worked example (.csv) ↗
Keep your own record
Use the result within its scope
Confirm the actual contract, ownership, settlement validity and payment route before acting. This example is not a valuation, lending decision, personal financial advice or a recommendation to end an agreement.
Reference sources
Earlier articles on this subject
- How Does A Parts Swap Work? ↗ — 2022-06-20, Maria Baldwin.
- Factors Which Affect Vehicle Valuations ↗ — 2022-03-15, Maria Baldwin.
- Business Car Finance – A Need For Any Trade ↗ — 2021-09-07, Maria Baldwin.